Moving into or out of a managed property—like an apartment building, condo, or co-op—often involves more than just packing boxes and hiring a moving company. One crucial document that frequently arises during this process is the “certificate of insurance for movers” (COI). This seemingly small detail can become a major hurdle if not handled correctly and in advance.
A COI is a formal document proving your moving company carries active insurance coverage for potential damages or accidents. Many building management companies require a “COI for movers” to protect themselves from liability for any incidents that might occur during your move, such as property damage to common areas or injuries sustained by workers. Understanding these “building insurance requirements moving” is essential for a smooth, stress-free relocation, especially when arranging an apartment moving service.
💡 Key Takeaway: A Certificate of Insurance (COI) from your movers is often a mandatory requirement for moving into or out of managed buildings, proving they have adequate coverage for potential damages or accidents.
Understanding the Certificate of Insurance (COI)
1. What is a COI and Why Do Buildings Require It?
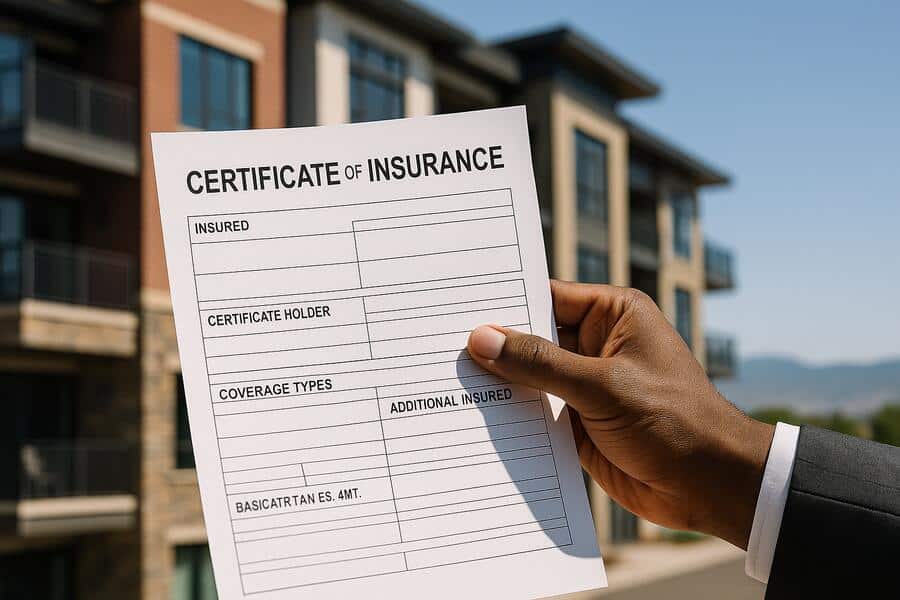
At its core, a Certificate of Insurance is a one-page document issued by a moving company’s insurance provider. It summarizes the key details of the mover’s active insurance policies, serving as proof of coverage.
- Proof of Coverage: It confirms that the moving company has essential insurance, typically including general liability and worker’s compensation.
- Risk Mitigation for Buildings: Managed properties require COIs to protect themselves from liability. If a mover accidentally damages a hallway wall, an elevator, or if a moving crew member gets injured on their property, the building wants assurance that the mover’s insurance will cover the costs, not the building’s or your own.
- Mandatory Access: Without an approved COI on file by moving day, your building management might deny the movers access to loading docks, freight elevators, or even the building itself. This can lead to significant delays, rescheduling fees, and immense stress.
2. Key Information Found on a COI
While the exact details can vary, a typical “certificate of insurance for movers” will include the following vital information:
- Insured’s Name: The legal name of the moving company.
- Insurance Company: The name of the insurer providing the coverage.
- Policy Numbers: The unique identification numbers for each insurance policy.
- Coverage Types and Limits:
- General Liability: Covers property damage and bodily injury to third parties. Limits often range from $1 million to $2 million per occurrence.
- Worker’s Compensation: Covers medical expenses and lost wages for moving company employees injured on the job.
- Auto Liability: Covers damages or injuries caused by the moving truck.
- Cargo Liability: (Often separate from the general COI, but important for your goods) Covers damage or loss to your actual belongings during transit. Federal regulations mandate minimum cargo liability coverage for interstate movers (e.g., $5,000 per vehicle, $10,000 per occurrence).
- Certificate Holder: This is typically your building’s management company, HOA, or landlord, who will be listed as an “Additional Insured” on the policy for the duration of the move. This is a critical requirement for most buildings.
- Policy Period: The effective dates when the insurance policies are active.
💡 Key Takeaway: A COI provides proof of a moving company’s general liability, worker’s compensation, and sometimes auto liability, with your building typically listed as an “Additional Insured” to protect against liabilities during the move.
Coordinating Your COI: A Step-by-Step Guide
3. How to Obtain and Coordinate the COI
The process of getting and submitting a “COI for movers” should be initiated well in advance of your moving date to avoid last-minute complications.
- Contact Your Building Management Early: As soon as your moving date is firm, reach out to your building management (HOA, landlord, property manager). Ask specifically about their “building insurance requirements moving.” They will provide you with their exact requirements, including:
- The minimum coverage amounts they require for general liability and worker’s compensation.
- The exact legal name and address they need listed as the “Certificate Holder” and “Additional Insured.”
- Any specific language or clauses they need included on the COI.
- Their preferred method for receiving the COI (email, fax).
- Any deadlines for submission.
- Communicate Requirements to Your Mover: Forward all of your building’s precise COI requirements to your chosen moving company. Reputable movers are accustomed to these requests and have established procedures for obtaining COIs from their insurance providers.
- Mover Requests COI: Your moving company will contact their insurance carrier to generate the COI with your building’s specific details listed as an additional insured.
- Review and Submit: Once the mover sends you the COI, review it carefully to ensure all details—especially the building’s name, address, and additional insured status—are correct and match your building’s requirements. Then, submit it to your building management within their specified timeframe.
4. Common Building Insurance Requirements and Potential Issues
While requirements are generally similar, certain details can cause issues if not addressed proactively.
- Specific Coverage Limits: Some buildings, especially high-value properties, may require higher liability limits (e.g., $2 million instead of $1 million). Ensure your mover’s policy meets these.
- “Additional Insured” Language: The exact wording for adding your building as an “Additional Insured” can be particular. Always provide the mover with the building’s precise wording.
- Proof of Worker’s Comp: Most buildings insist on worker’s compensation coverage to protect against liability for mover injuries. Verify this is included.
- Timing and Deadlines: Many buildings require the COI several days or even a week in advance. Don’t wait until the day before your move, as generating a COI can take 24-48 hours.
- Elevator Reservations: Often, submitting an approved COI is a prerequisite for reserving freight elevators or loading dock times. Plan accordingly.
COI Coordination Checklist
| Action Item | When to Complete | Details/Notes |
|---|---|---|
| Contact Building Management | 3-4 weeks before move | Get exact COI requirements (limits, add. insured name, deadlines) |
| Forward Requirements to Mover | Immediately after getting them | Ensure mover has all necessary info to request COI |
| Mover Submits Request to Insurer | ASAP (can take 1-2 business days) | Follow up with mover if not received promptly |
| Review COI from Mover | Upon receipt | Verify all building details, coverage, and dates are correct |
| Submit COI to Building Management | At least 3-5 business days before move | Confirm receipt and approval with building management |
💡 Key Takeaway: Proactively contact your building for precise COI requirements, relay them accurately to your mover, and submit the verified COI well in advance to avoid moving day delays.
Conclusion
The “certificate of insurance for movers” is a critical document that can make or break your moving day, especially in managed properties. By understanding what a COI is, why your building requires it, and meticulously coordinating its submission with both your building management and your moving company well in advance, you can avoid unnecessary stress and delays. Consider it a non-negotiable part of your moving checklist, ensuring a smooth transition into or out of your home while keeping all parties protected.
Have questions about how to building insurance requirements moving? Reach out to our team today.
Frequently Asked Questions About Moving Company Certificates of Insurance
What happens if I don’t provide a COI for my movers?
If you don’t provide an approved COI by your building’s deadline, your building management may deny your movers access to the building, its loading docks, or freight elevators. This can lead to significant delays, force you to reschedule your move, and result in additional fees from your moving company. In some cases, it could even prevent your move from happening on the scheduled day.
Who is responsible for getting the COI?
While you, the tenant, are responsible for ensuring the COI is provided to your building, the moving company is responsible for obtaining it from their insurance carrier. You must provide your moving company with all the specific details and requirements from your building management for them to generate an accurate COI.
Does the COI cover damage to my personal belongings?
A standard COI primarily demonstrates the mover’s general liability and worker’s compensation coverage, protecting the building from liability. Damage to your personal belongings (cargo) is covered under the moving company’s separate cargo liability insurance. For interstate moves, federal law requires movers to offer at least two levels of cargo liability: Released Value Protection (basic, low coverage) and Full Value Protection (more comprehensive, but costs extra).
How far in advance should I request a COI?
You should request the COI from your moving company at least 1-2 weeks before your moving date, or as soon as you have your building’s exact requirements. Generating a COI can take 24-48 business hours, and your building management may require it several business days before your move to process it. Proactive planning is key.